Ryman Hospitality Properties closed its acquisition of Grande Lakes Orlando on September 1, 2026, moving the transaction from a signed deal into an owned operating asset. The September 1 Form 8-K says the aggregate purchase price paid was approximately $1.38 billion and that funding came from an equity offering, a $700 million notes placement and cash on hand.
For FP&A, those financing sources should stay separate from the operating forecast. Ryman’s revised 2026 outlook adds an expected Grande Lakes contribution of $11 million to $14 million of operating income and $30 million to $35 million of Adjusted EBITDAre for the remainder of 2026. The asset is closed; those operating figures are still forecasts, not post-close actuals.
What changed and what it means
Grande Lakes adds expected 2026 operating contribution and lifts consolidated operating-income and Adjusted EBITDAre midpoints, while financing and dilution change other consolidated measures.
- Decision affected
- Rebase the 2026 consolidated forecast after closing while keeping acquisition financing, purchase consideration and expected operating contribution in separate states.
- Evidence in brief
- SEC closing, equity, debt and purchase-agreement records plus Ryman guidance establish the funding, closing and forecast states.
- What remains unresolved
- Cash on hand, final post-closing adjustments, total acquisition costs, GAAP purchase-price allocations and actual post-close property results are not disclosed.
- Next verification
- Reconcile the first post-close filing to the September 1 property contribution ranges and any final purchase-price or purchase-accounting disclosures.
Key takeaways
- Ryman completed the Grande Lakes acquisition on September 1 for an aggregate purchase price paid of approximately $1.38 billion, subject to the transaction’s adjustment mechanics.
- The financing stack included 5,865,000 shares sold at $117 each, $700 million principal of 6.250% senior notes due 2035 and an undisclosed amount of cash on hand.
- Grande Lakes is forecast to contribute $11 million to $14 million of 2026 operating income and $30 million to $35 million of Adjusted EBITDAre; the midpoints match the increases in Ryman’s consolidated guidance for those two measures.
- Ryman did not disclose a separate Grande Lakes Adjusted FFO contribution, so the $17 million increase in consolidated Adjusted FFO midpoint should not be relabeled as property-level contribution.
- Final post-closing adjustments, the cash-on-hand amount, total acquisition transaction costs and GAAP purchase-price allocations remain undisclosed.
The $1.38bn purchase price is not the financing total
The transaction starts with a contractual purchase price of $1.38 billion, but the purchase agreement makes that amount subject to specified closing and post-closing adjustments. Ryman had already placed $50 million of earnest money in escrow at signing; the agreement says that amount is credited against the purchase price at closing rather than added as a separate acquisition cost.
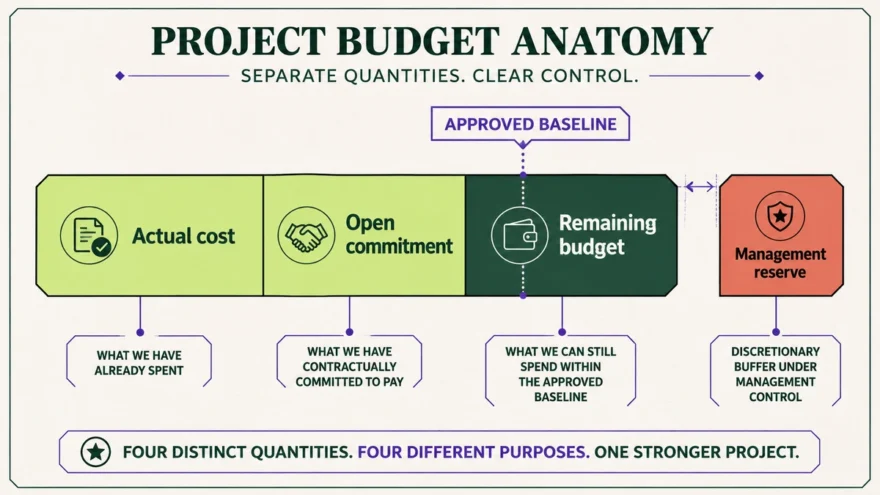
| Financing state | Disclosed amount | FP&A treatment |
|---|---|---|
| Common equity | 5.865m shares at $117; about $658m net proceeds | Capital source, not property revenue or purchase consideration |
| Senior notes | $700m principal; 6.250%; due February 15, 2035 | Debt source; principal is not the same as net cash proceeds |
| Cash on hand | Amount not disclosed | Use only as a disclosed funding category; do not backsolve a residual |
| Earnest money | $50m deposited at signing | Purchase-price credit at closing, not a fourth funding source |
The equity-closing filing records approximately $658 million of net proceeds after underwriting discounts, commissions and estimated offering expenses. The notes filing records $700 million of principal and states that the proceeds were intended to fund part of the purchase price and related fees and expenses. Ryman’s August 25 notes-closing release said aggregate net proceeds were expected to be approximately $689 million after discounts, commissions and estimated offering expenses.
That makes a simple residual calculation unsafe. Subtracting $658 million and $689 million from $1.38 billion would mix an approximate, adjustable purchase price with one actual equity net-proceeds figure, one expected debt net-proceeds figure and financing that also covers related fees and expenses. Ryman has not disclosed the exact cash-on-hand contribution.
Bridge the closed asset into the revised 2026 outlook
Ryman’s September 1 guidance table provides a cleaner operating bridge than the funding stack does. The property-level ranges for operating income and Adjusted EBITDAre can be compared directly with the change in consolidated guidance.
| 2026 measure | Prior midpoint | New midpoint | Midpoint change | Grande Lakes disclosure |
|---|---|---|---|---|
| Consolidated operating income | $550.4m | $562.9m | +$12.5m | $11m-$14m; midpoint $12.5m |
| Consolidated Adjusted EBITDAre | $894.0m | $926.5m | +$32.5m | $30m-$35m; midpoint $32.5m |
| Adjusted FFO available to common stockholders and unit holders | $604.5m | $621.5m | +$17.0m | Not separately disclosed |
| Net income | $283.0m | $279.8m | -$3.3m | Not separately disclosed |
| Diluted EPS | $4.11 | $3.93 | -$0.18 | Not separately disclosed |
| Adjusted FFO per diluted share/unit | $9.13 | $9.08 | -$0.05 | Not separately disclosed |
The two property-level midpoints exactly equal the consolidated midpoint increases for operating income and Adjusted EBITDAre. That is a useful disclosed bridge. It does not extend automatically to Adjusted FFO: Ryman raised the consolidated Adjusted FFO midpoint by $17 million but did not provide a separate property-level Adjusted FFO figure.
Keep financing effects out of the property contribution line
The revised reconciliation also changes measures below the property operating contribution. Net interest expense midpoint rises from $249.875 million to $265.875 million, an increase of $16 million. Depreciation and amortization midpoint rises from $312.25 million to $332.25 million, an increase of $20 million. The estimated weighted average diluted share count rises from 68.4 million to 70.7 million after the August equity issuance. The prior values are also visible in Ryman’s August 6 outlook.
Those movements help explain why an increase in consolidated Adjusted EBITDAre can coexist with lower net-income and per-share midpoints, but Ryman has not published a complete causal waterfall assigning every dollar of the interest or depreciation change solely to Grande Lakes. FP&A should therefore retain those lines as consolidated forecast changes unless the company provides a more specific attribution.
Use three linked schedules after the acquisition-date gate
A post-close model can keep the transaction understandable by maintaining three linked schedules:
- Capital sources and uses: record equity gross and net proceeds, debt principal and disclosed net proceeds, cash only when quantified, and financing or acquisition fees separately.
- Closing and consideration: record the approximately $1.38 billion purchase price paid, the $50 million earnest-money credit and subsequent Article X adjustments without treating them as operating expenses.
- Operating forecast: bring in only the expected post-close property contribution and the separately disclosed consolidated forecast changes, including share-count, interest and depreciation assumptions.
The legal perimeter includes the two hotels, the Ritz-Carlton golf club and defined asset-related property, including specified personal property, operating equipment, consumables, contracts, permits and certain transferable intangibles. It also excludes categories such as Marriott-owned or Marriott-licensed systems and other third-party property. The purchase agreement’s Section 2.4 allocation is for transfer-tax filings and permits separate tax allocations; it is not a disclosed GAAP purchase-price allocation.
What remains forecast or unresolved after September 1
Ownership is now an actual state. Operating contribution is not. Ryman says the revised outlook includes the expected Grande Lakes contribution based on information available September 1, and its same-store Hospitality RevPAR growth guidance remains 3.5% to 4.5% while explicitly excluding Grande Lakes.
The purchase agreement also keeps some closing economics open. Buyer must deliver a preliminary post-closing statement within 180 days, and the Article X adjustment obligations survive until 210 days after closing while estimated and actual prorations are reconciled. Those mechanics cover operating items such as revenues and expenses around the cut-off, inventory, accounts payable, booking deposits and other specified prorations.
Ryman has not disclosed the final cash-on-hand contribution, a total acquisition transaction-cost figure, a final GAAP allocation to land, buildings, identifiable intangibles or goodwill, or any actual post-close Grande Lakes revenue, operating income or Adjusted EBITDAre. Until those records arrive, the September 1 close and the September 1 forecast should remain separate states in the model.