Dell’s Sept. 1 SEC-furnished Q2 FY27 release reports $46.971 billion of total revenue for the quarter ended July 31, 2026. Inside that total, Dell says it booked $60.9 billion of AI-server orders, recognized $16.401 billion of AI-optimized server revenue and ended the quarter with $95 billion of AI backlog. The company also raised full-year revenue guidance from a previous $167 billion midpoint to $192 billion and raised its AI-server revenue guide from $60 billion to $74 billion.
For FP&A, those numbers are not one revenue measure. Orders are booked demand, backlog is a reported future-work measure, $16.401 billion is Q2 recognized revenue, and $74 billion and $192 billion are forward-looking full-year guidance. Dell does not publish a quarter-by-quarter schedule showing how the $95 billion backlog will convert into FY27 revenue, so the forecast has to preserve the states rather than collapse them.
What changed and what it means
Dell’s $60.9bn of Q2 AI-server orders and $95bn ending backlog do not by themselves close the $41.467bn H2 recognized-revenue requirement implied by the $74bn FY27 AI-server guide.
- Decision affected
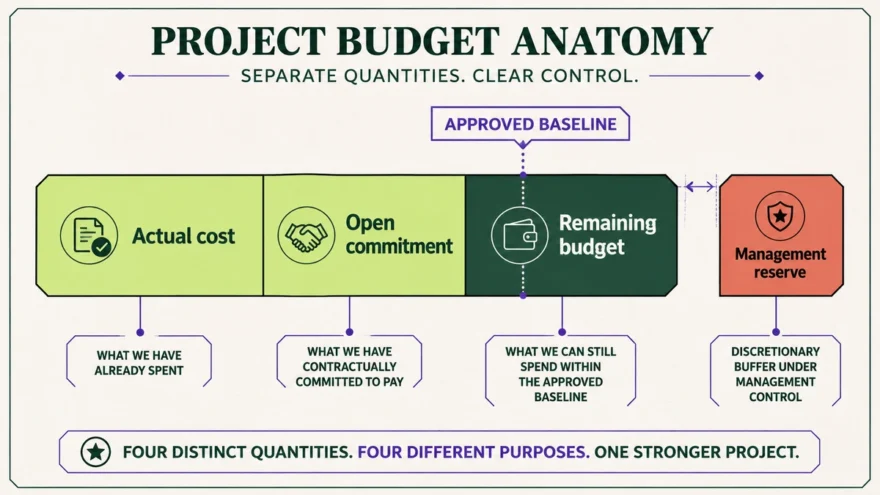
- Rebase the FY27 forecast while keeping Dell AI-server orders, backlog, recognized revenue and full-year guidance in separate evidence states.
- Evidence in brief
- Dell reported $46.971bn of Q2 revenue, $60.9bn of AI-server orders, $16.401bn of Q2 AI-server revenue, $32.533bn for H1, $95bn ending backlog and raised FY27 revenue and AI-server guidance to $192bn and $74bn.
- What remains unresolved
- Dell has not disclosed a complete order-to-backlog roll-forward, a quarter-by-quarter backlog-conversion schedule, an AI-server margin by backlog cohort or a numeric full-year cash-flow guide.
- Next verification
- Preserve the disclosed states, test the $41.467bn H2 revenue requirement against Q3 execution and supply conditions, and update the bridge when Dell reports Q3 FY27.
Key takeaways
- Dell booked $60.9 billion of Q2 AI-server orders, recognized $16.401 billion of Q2 AI-server revenue and ended with $95 billion of AI backlog.
- First-half AI-server revenue was $32.533 billion, leaving about $41.467 billion of additional H2 recognized revenue required to reach the $74 billion FY27 guide.
- The $95 billion backlog is not a disclosed FY27 conversion schedule, and Dell does not provide the cancellations, modifications or other adjustments needed for a complete public backlog roll-forward.
- Dell’s margin, supply and cash disclosures support forecast assumptions, but they do not turn full-year revenue guidance into guaranteed revenue or a numeric full-year cash-flow forecast.
The $25bn guide increase starts from a different evidence state
Dell’s May 28 Q1 results set the immediate prior full-year state. At that point Dell expected FY27 revenue of $165 billion to $169 billion, with a $167 billion midpoint, and roughly $60 billion of AI-optimized server revenue. The September update lifts the consolidated midpoint by $25 billion to $192 billion and the AI-server figure by $14 billion to $74 billion.
| Measure | Previous state | Current state | FP&A treatment |
|---|---|---|---|
| Consolidated FY27 revenue | $165bn-$169bn; $167bn midpoint | $192bn guidance/midpoint | Current full-year management forecast; not recognized revenue |
| FY27 AI-server revenue | About $60bn | $74bn | Current full-year AI-server guidance; not backlog |
| Q2 consolidated revenue | Q2 guide of $44bn-$45bn | $46.971bn actual | Closed-period actual |
The current release presents $192 billion as the updated full-year revenue figure, while management calls it the midpoint on the earnings call. It does not publish a new consolidated range alongside that midpoint. FP&A should therefore preserve the disclosed $192 billion point rather than manufacture upper and lower bounds that Dell has not provided.
Build the AI bridge from recognized revenue, not from backlog
Dell’s Q2 tables report $32.533 billion of AI-optimized server revenue for the first six months of FY27. Against the $74 billion full-year guide, that leaves $41.467 billion of additional recognized AI-server revenue required in the second half. That is Finance Circuit arithmetic: $74.000 billion minus $32.533 billion. It is not a Dell-disclosed promise that $41.467 billion of the current backlog will convert by year-end.
| State | Amount | Classification | Do not assume |
|---|---|---|---|
| Q2 AI-server orders | $60.9bn | Booked demand metric | That orders equal revenue or ending backlog |
| Q2 ending AI backlog | $95bn | Reported backlog | That all backlog converts in FY27 |
| Q2 AI-server revenue | $16.401bn | Recognized quarterly revenue | That it represents the same order cohort |
| H1 AI-server revenue | $32.533bn | Recognized first-half revenue | That the H2 run rate is already secured |
| H2 revenue required to reach FY27 guide | $41.467bn | Finance Circuit calculation | That this is Dell’s backlog-conversion commitment |
| FY27 AI-server revenue | $74bn | Full-year guidance | That guidance is guaranteed or already booked |
The Q2 earnings call adds a useful near-term assumption: Dell expects about $19 billion of AI-server revenue in Q3. If the $74 billion full-year guide and that Q3 assumption are both achieved, about $22.467 billion would remain for Q4 after the $32.533 billion first-half actual. That $22.467 billion is another Finance Circuit calculation, not formal Q4 guidance and not evidence of which backlog cohort would convert.
Dell has not published a complete order-to-backlog roll-forward
There is a second reason not to convert the headline numbers mechanically. Dell said on its Q1 FY27 earnings call that it ended Q1 with $51.3 billion of AI backlog. Adding Q2 orders of $60.9 billion and subtracting Q2 AI-server revenue of $16.401 billion produces about $95.799 billion, not the reported $95 billion ending backlog.
That difference is not evidence of $0.799 billion of cancellations. The order and backlog headlines are rounded, and Dell has not disclosed a public bridge covering cancellations, contract changes, scope differences or other movements. The safe control is to store the reported order, backlog and revenue measures separately and leave the unexplained roll-forward difference unallocated until Dell supplies evidence.
Supply and margin assumptions sit between demand and revenue
Management said on the Q2 call that demand outstrips supply in traditional servers and that Dell is supply constrained. It also said its second-half gross-margin-rate outlook had improved over the prior 90 days. Those comments matter because booked demand can only become revenue after Dell obtains components, configures and delivers systems, and satisfies the conditions for recognition.
Q2 gives FP&A actual margin anchors. Dell reported a 21.1% non-GAAP gross-margin rate, non-GAAP operating expenses equal to 8.5% of revenue, a 12.6% non-GAAP operating margin and a 15.0% ISG operating-income rate. For the full year, management expects operating expenses to be approximately 8% of revenue and says gross-margin rates excluding the mix effect of AI servers are up year over year. Dell does not disclose an AI-server gross-margin rate or a backlog-cohort margin schedule, so those should not be invented to explain the $74 billion revenue guide.
Revenue guidance does not supply a full-year cash forecast
Dell reported $2.225 billion of Q2 cash flow from operating activities and $8.149 billion of adjusted free cash flow. The measures are not interchangeable: adjusted free cash flow is a non-GAAP measure with its own reconciliation. The materials reviewed for this article do not provide a numeric FY27 operating-cash-flow or adjusted-free-cash-flow guide.
That means the $25 billion increase in the revenue midpoint should not be translated mechanically into a cash uplift. FP&A still needs working-capital, supplier-payment, inventory, capital-spending and other cash assumptions outside the revenue bridge.
What FP&A should lock into the next forecast version
- Close H1 on recognized revenue. Use $32.533 billion as the first-half AI-server actual and retain $41.467 billion as the arithmetic H2 requirement to reach the $74 billion guide.
- Keep order and backlog states separate. Store $60.9 billion of Q2 orders and $95 billion of ending backlog as reported management metrics, not revenue substitutes.
- Version the Q3 assumption. Record the approximately $19 billion Q3 AI-server revenue expectation with its source date; do not relabel the implied $22.467 billion Q4 remainder as Dell guidance.
- Attach operational dependencies. Track supply availability and delivery execution as drivers that can change conversion timing.
- Keep margin and cash in their own bridges. Do not use a revenue guide to infer an undisclosed AI-server margin or full-year cash-flow outcome.
- Preserve the actuals-to-forecast handoff. Record source date, evidence state, owner and update trigger so the next Dell disclosure changes the current forecast without rewriting the historical state.
The useful Dell signal is not that $95 billion of backlog “supports” $74 billion of FY27 AI-server revenue in a mechanical sense. It is that Dell has disclosed strong booked demand, a large ending backlog, $32.533 billion of first-half recognized AI-server revenue and a materially higher full-year forecast while still describing supply as constrained. FP&A can use all of those facts, but only if the model keeps each one in the state Dell actually disclosed.