Cash arrives every day. The operating question is not whether it reaches the bank account, but how long it sits there before anyone can say which customer sent it and which invoices it clears. That gap is where cash application automation either earns its cost or builds a different backlog.
Most buying conversations open with a match rate. A more useful starting question is narrower: which remittance sources actually reach the team, what does each one contain, and who decides what happens when the money and the paperwork disagree?
Quick answer
Automation that matches faster without owned tolerances and exception ageing converts customer deductions into unapplied cash and hides commercial disputes inside a cash figure.
Decision: Approve cash application automation only after each remittance source, matching rule, deduction tolerance, exception population and posting authority has a named owner and a measured rate.
Key takeaways
- Cash application automation is three separable jobs: identify the payer, obtain the remittance detail, and apply the money to open items. Each fails differently and each needs its own measured rate.
- Electronic payment growth moved the problem rather than removing it. Funds now settle faster than the remittance data that explains them.
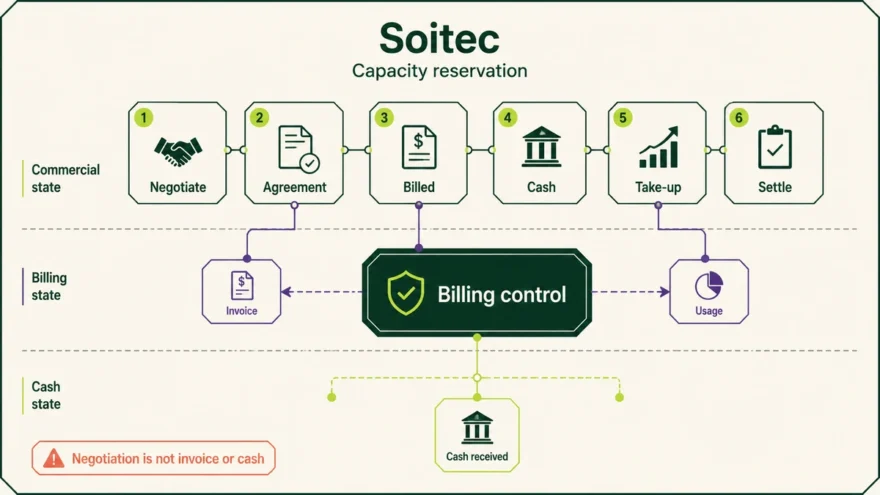
- A short payment is a disposition decision, not a matching failure. Systems that treat every difference as an exception will bury real deductions in an unapplied queue.
- Unapplied, unidentified and on-account balances are different populations with different owners. Collapsing them into one figure hides the ageing that matters.
- A single touchless percentage is not evidence. Posting a receipt and clearing an invoice are separate events, and vendor documentation shows systems that can do the first without the second.
What cash application automation owns, and what it does not
Cash application is the step that converts an incoming payment into a cleared receivable. It begins when the bank reports money received and ends when specific open items are settled, or when the residual is deliberately parked somewhere with a named owner.
Three adjacent processes are routinely confused with it. Collections is the work of getting a customer to pay at all, measured on contact, promises and overdue balances rather than matching accuracy; those requirements are set out in a separate collections software evaluation. Bank reconciliation proves the ledger balance agrees with the bank statement, a different assertion with different evidence, covered under account reconciliation controls. Accounts payable invoice automation solves a structurally similar problem in the opposite direction, and its stage-gate design is worth reading as a comparison in AP-side invoice matching and exception design.
Cash application sits inside the wider flow described in the order-to-cash process map. That map treats it as one stage among several. This article treats the stage itself as the design problem.
Why electronic payment growth did not remove the matching problem
A common assumption is that cash application difficulty is a paper problem that will retire with the check. The published payment data does not support that conclusion.
The Association for Financial Professionals reports that checks account for 26% of business-to-business payments, down from 33% in 2022, based on responses from 223 financial professionals in its 2025 Digital Payments Survey. The Federal Reserve records check payments falling to 9.2 billion by number and $24.45 trillion by value in 2024, a decline of 5.9% a year by number since 2021, in its national payment volumes data. Nacha reports the ACH Network handled 35.2 billion payments worth $93 trillion in 2025, with business-to-business volume growing almost 10% to close to 8.1 billion payments, in its 2025 network results.
Read together, those figures describe a migration rather than a resolution. Volume is moving onto rails that settle funds quickly while carrying explanatory detail inconsistently. A check and its remittance advice usually travel in the same envelope. An electronic credit and its advice frequently do not travel together at all, because the advice may be emailed separately, posted to a customer portal, or compressed into a bank narrative field that truncates the invoice list. The same AFP survey found 40% of organisations naming updated payment file formats as a priority in their next payments strategy, which is a reasonable proxy for how unsettled this data layer remains.
A business case built purely on removing keystrokes will therefore understate the work. The harder cost is reassembling payment and explanation from two channels arriving at different times in different shapes.
Map the receipt-to-clearing chain before selecting software
Before comparing products, write down the chain the money actually travels and name an owner at each transfer. Most disappointing implementations are traceable to a stage that nobody owned.
| Stage | Input | Decision taken | Evidence retained |
|---|---|---|---|
| Receipt notification | Bank statement or intraday file | Is this a customer receipt or another credit? | Bank reference, value date, amount |
| Payer identification | Payer name, account details, narrative | Which customer account is this? | Identification method and confidence |
| Remittance acquisition | Advice by email, portal, EDI or addenda | Do we have an itemised explanation? | Source, retrieval time, completeness |
| Matching | Open items and remittance lines | Which invoices does this settle? | Rule that fired, items proposed |
| Difference disposition | Residual amount and reason | Deduction, discount, write-off or hold? | Reason code, approver, threshold |
| Posting and clearing | Approved application | Post the receipt, settle the item | Journal reference, settlement record |
| Exception ageing | Anything unresolved | Who owns this, and by when? | Population, age, named owner |
Two rows deserve attention because vendors rarely separate them. Payer identification and invoice matching are distinct operations with distinct failure modes. A receipt can be confidently assigned to a customer and still not be applied to anything, and a remittance can list invoice numbers belonging to a customer the system has not recognised.
Where the remittance data actually comes from
Two supply routes feed the matching engine, and they behave differently enough to be scoped separately.
Bank data and lockbox files
The starting material is a bank file, and its format determines how much structure the system receives. Microsoft documents three formats built into Dynamics 365 Finance for advanced bank reconciliation, ISO 20022, BAI2 and MT940, with the ability to extend to other formats, in its advanced bank reconciliation overview.
The more instructive detail sits in the setup documentation. Microsoft notes that transformation files are built for the standard format, and that because banks often diverge from it the transformation may have to be updated to map to a specific bank statement format, in its guidance on the bank statement import process. Naming a standard format in a requirements document does not mean a given bank file will parse without mapping work, and a multi-bank estate multiplies that work per relationship. The channel decisions determining which files arrive, and when, are set out in the guide to bank connectivity channels.
Lockbox remains a live input rather than a legacy one. SAP lists lockbox files alongside bank statement items as a matching input for its machine learning services in the documentation for machine learning based cash application. Where a provider keys remittance detail from paper, the quality of that keying directly affects the match rate and should be measured as supplier performance.
Remittance capture across email, portal, PDF and EDI
Remittance advice arrives through channels differing in structure and in cost to obtain. Structured EDI and ACH addenda data can be parsed directly. Emailed PDFs and spreadsheets require extraction. Customer accounts payable portals require credentials, navigation and periodic re-authentication, a recurring operational burden rather than a one-time integration.
SAP documents extraction of relevant information from payment advice documents for use in matching and clearing, and separately notes that structured payment advice information can be enabled for matching. Extracting a figure from a PDF is not equivalent to receiving a structured advice, and the two produce different confidence levels for the same customer.
Decide early whether to pursue remittance at source. Asking a large customer to send structured advice to a dedicated address, or to carry invoice references in the payment itself, often removes more manual work than any extraction feature. That request belongs in customer onboarding, not in the software evaluation.
How the match is actually made
Identification and application are sequential, and each documented approach treats them as separate problems.
Customer identification precedes invoice matching
NetSuite displays imported bank lines with a positive amount and assigns a customer where a match is found. Where none is found, a user selects the customer and can create a customer mapping rule, saving an association between the Payor and Memo fields of the bank line and that customer for future use, according to Oracle documentation on automated cash application in NetSuite. Dynamics 365 Finance offers automatic customer account matching comparing the related bank account on the statement line with the customer IBAN and then the customer bank account number, described in Microsoft guidance on cash application in advanced bank reconciliation. SAP provides customer account identification as a separate machine learning service from line-item matching.
A mapping rule is a durable assumption written by whoever happened to clear that item. A rule keyed on a payer name will survive a customer reorganisation, a shared service centre paying for several legal entities, or a factoring arrangement, and will keep applying quietly after it has become wrong. Rule creation deserves the same review as any master data change.
Matching rules, tolerances and multi-invoice payments
Matching rules are filters over statement lines and open items. Microsoft describes a rule as a set of criteria filtering bank statement lines and finance transaction lines, grouped into rule sets that execute in sequence from top to bottom, in its documentation on bank reconciliation matching rules. Rule order is a design decision with financial consequences, because an early permissive rule consumes items a later precise rule would have matched correctly.
One default deserves explicit attention during configuration. Microsoft states that by default matching rules match to the first bank document meeting the rule criteria, and that a parameter must be turned on to require manual matching when the rules find multiple documents matching on amount. Where identical invoice values repeat, accepting that default means the system makes a silent choice among equally plausible candidates. The entry will look matched, and will be wrong at the invoice level while remaining correct at the customer level, which makes it hard to detect later.
Multi-invoice payments are the normal case in business-to-business receivables. SAP lists one item for many invoices among the complex matchings its services handle. NetSuite documents that where a bank line specifies invoice numbers the system displays the invoices the payment will be applied to, and otherwise provides a list of suggested invoices, allocating amounts automatically with the option to adjust. Acceptance testing should include a payment covering many invoices, one spanning more than one legal entity, and one settling some invoices in full and another in part.
Differences, deductions and exception populations
Most of the residual work in cash application is deciding what a difference means and who owns it.
Deductions and short pays are a disposition decision
A short payment is a customer paying less than the invoiced amount, usually on purpose. Common categories are pricing differences, quantity or shortage claims, damaged goods, promotional and trade allowances, freight terms, unauthorised deductions, and early settlement discounts taken outside agreed terms.
The error to avoid is treating every residual as a matching problem. The match may be entirely correct: the customer intended to pay those invoices and intended to pay less. The system should classify the residual, route it to whoever can approve or dispute it, and clear the invoice to the extent the customer has settled it. Refusing to apply anything until the difference is resolved converts a deduction into an unapplied balance and hides a commercial dispute inside a cash figure.
Tolerance design carries the load, and needs four parameters rather than one: the value below which a difference is written off without review, the reason code recorded, the ledger account it posts to, and the approval level required above that value. Set the threshold too high and disputes disappear into the profit and loss without anyone seeing a pattern. Set it too low and the exception queue fills with rounding.
Documented handling of one narrow case is instructive. Microsoft describes a feature applying customer cash discounts during automatic settlement through reconciliation rules, so discounts apply consistently whether invoices settle manually or automatically, which it states eliminates residual open balances caused by unapplied discounts. That is the pattern worth replicating for other deduction categories: recognise the reason, apply the correct treatment, and stop generating a residual someone must interpret later.
Unapplied, unidentified and on-account are separate populations
These three states are frequently reported as one number, and the aggregate is close to useless for management.
An unidentified receipt is money whose payer is unknown. Its resolution route is investigation with the bank, the payer or the sales team, and its risk grows with age because the trail cools. An unapplied receipt has a known customer but no allocation to specific invoices, usually because remittance detail is missing; its resolution route is a remittance request. An on-account balance is a deliberate decision to hold funds against a customer without allocation, often pending a dispute or credit, and it should carry an expected clearing date.
Each population needs its own ageing profile and named owner. A suspense or clearing account holding these balances should be reconciled on the same cadence as any other balance sheet account, with items ageing past a defined threshold escalated rather than carried forward. If one person can both create the application rule and clear the suspense balance it produces, the control is incomplete regardless of how accurate the matching engine is.
ERP posting, integration and where subledger authority stays
Whatever proposes the match, the accounts receivable subledger remains the authoritative record of what a customer owes. A tool holding application decisions outside the subledger creates a second version of the truth that has to be reconciled, which is the cost acquiring it was meant to remove.
A useful boundary is that upstream components may propose, enrich and score, while the enterprise resource planning system posts and clears. Microsoft documentation shows a version of this inside one product: reconciliation matching rule results can be reviewed and approved before transactions post, held on a pending review tab, with users able to approve or reject them within the worksheet. Where that gate exists, someone must be assigned to operate it, or it becomes a queue rather than a control.
The reversal path matters as much and is often untested. Microsoft documents cancellation of incorrectly posted customer payment journals from the reconciliation worksheet, noting that where the invoice was settled during posting it is also unsettled at cancellation. Confirm that behaviour in a test environment before go-live, because an application that cannot be cleanly reversed will be fixed by manual journals against receivables.
Controls that must survive automation
Automating cash application changes who performs the work but should not change who is accountable for it. Six controls carry most of the risk.
- Segregation of duties. Creating a customer mapping rule, approving a deduction write-off and clearing a suspense balance should not all sit with one person.
- Rule change control. Matching rules determine accounting outcomes. Changes need a request, a reviewer and a dated record, as a posting configuration change would.
- Threshold governance. Write-off tolerances need an owner, a review cadence and a report showing what was written off under them by reason code.
- Audit trail. For any applied receipt the record should show which rule fired, what remittance evidence supported it, whether a person intervened, and who approved anything above a threshold.
- Exception ownership. Every exception population needs a named owner and an ageing threshold triggering escalation rather than a rolling carry-forward.
- Master data discipline. Payer aliases, bank account details and customer hierarchies drive identification. A stale alias produces confident wrong answers.
Measure auto-match, auto-post and first-pass yield separately
A single touchless percentage invites the wrong conclusion, and the vendor documentation shows why. Microsoft distinguishes generating a customer payment, which posts a payment journal without settling any open invoices, from settling transactions, which also settles the matched invoice. A system can report a receipt as processed while the invoice stays open, so a headline rate counting the first event overstates the outcome an accounts receivable team cares about.
| Measure | Definition | Why it misleads on its own |
|---|---|---|
| Identification rate | Receipts assigned to a customer without a person | High identification can coexist with almost no application |
| Auto-match rate | Receipts matched to specific open items by rule | Counts proposals, not necessarily posted results |
| Auto-clear rate | Receipts posted and open items settled without touch | The number most vendors mean by touchless |
| First-pass yield | Applied correctly with no later correction | Only visible once reversals are counted against it |
| Exception ageing | Age profile per exception population | An improving match rate can hide a worsening tail |
| Rework rate | Applications later reversed or reallocated | Rises quietly when tolerances are set too loose |
Take a baseline before implementation, because without one any later figure is an assertion. Treat vendor claims of very high touchless rates as company-stated outcomes achieved in unstated conditions, since they depend on payment mix, remittance quality and customer concentration.
Software approaches documented as of 21 August 2026
The categories below describe documented scope, not comparative performance. Inclusion is representative rather than exhaustive, and vendor sources prove only what each company documents.
| Approach | Documented capability | Fits when |
|---|---|---|
| ERP-native matching, Dynamics 365 Finance | Statement import in ISO 20022, BAI2 and MT940; rule sets executing in sequence; actions to generate a customer payment or settle a customer invoice; optional review before posting | One primary ERP and a manageable number of bank relationships |
| ERP-native matching, NetSuite | Imported bank lines with customer assignment; customer mapping rules on Payor and Memo; automatic allocation across suggested invoices with manual adjustment | The subledger should stay the single place applications are decided |
| Machine learning service on the ERP, SAP | Receivables line-item matching and customer account identification trained on past manual actions; payment advice extraction; lockbox files as an input | Rule-based matching has plateaued and historical clearing data exists |
| Specialist accounts receivable platforms | Company-stated remittance aggregation, portal retrieval and deduction workflow across multiple ERPs | Several ERPs, heavy portal-based remittance, or a large deduction population |
| Bank and lockbox services | Keyed remittance capture and structured data delivery from paper and electronic receipts | Check volume remains material and keying is better placed with the provider |
The machine learning approaches carry a prerequisite worth surfacing in evaluation. SAP describes a model trained with data from past manual actions in order to apply that learning to new data. Where an organisation has recently migrated systems, or cleared inconsistently in the past, that training history may be thinner than it appears.
Approval checklist before commissioning cash application automation
- List every remittance source by channel, volume and structure, and record who retrieves each one today.
- Obtain a real file from each bank and confirm it parses without bespoke mapping, or budget the mapping.
- Baseline identification, match, clear and rework rates before any change.
- Decide the tolerance value, reason codes, posting account and approval level for deductions, and get them approved.
- Separate unapplied, unidentified and on-account balances in reporting, with an owner and ageing threshold for each.
- Confirm whether the default is silent first-match on ambiguous amounts, and set the parameter deliberately.
- Test reversal end to end, including whether a cancelled payment unsettles the invoice.
- Assign the review queue to a named person if a pre-posting approval gate is enabled.
- Run acceptance tests on multi-invoice, part-paid, cross-entity, duplicate-amount and wrong-customer scenarios.
- Agree who may create or change a matching rule, and how that change is recorded.
Frequently asked questions
What is cash application in simple terms?
Cash application is matching money a customer has paid to the specific invoices it settles, then posting that result so the receivable is cleared. It requires three things: knowing who paid, knowing what they were paying for, and deciding what to do with any difference between the amount received and the amount invoiced.
What is the difference between cash application and payment reconciliation?
Cash application allocates a customer receipt to open invoices in the receivables subledger. Payment reconciliation proves that recorded transactions agree with the bank statement. They use overlapping data and often the same import file, but they answer different questions and produce different evidence. A receipt can be reconciled to the bank while remaining unapplied to any invoice.
What software is used for cash application?
Three documented categories exist. Enterprise resource planning systems such as NetSuite and Dynamics 365 Finance include native matching against imported bank data. SAP offers machine learning services trained on past clearing actions. Specialist accounts receivable platforms add remittance aggregation and deduction workflow across several systems, and bank lockbox services capture remittance from paper receipts.
Why does unapplied cash keep growing after automation?
Usually because the system will not apply a receipt when the amount differs from the invoice, so genuine deductions become unapplied balances instead of classified disputes. Check the tolerance threshold, whether reason codes exist, and whether partial application is permitted. Growth also follows missing remittance detail rather than any weakness in the matching rules themselves.