General Motors entered an up-to-$4.5 billion inventory-financing arrangement with Procura Auto Parts on August 7, 2026. In its Form 8-K filed on August 11, GM said it may issue irrevocable payment undertakings to Procura, acting as paying agent, so Procura can advance funds to selected GM suppliers. Those suppliers, not Procura, are described as acquiring and holding inventory on GM’s behalf. The $4.5 billion figure is the maximum aggregate face amount of outstanding undertakings at any time, not an amount already funded or a disclosed value of parts in storage.
For procurement, the financing event and the supply-assurance decision are separate. The filed Master IPU Agreement says GM’s payment obligation can remain enforceable despite non-delivery, acceptance problems, quality defects, supplier insolvency, non-use and a failure to perfect a transfer or security interest. Funded inventory should therefore enter continuity coverage only after procurement can prove the specific parts are controlled, identifiable, conforming and releasable. The public filing does not disclose the participating suppliers, parts, utilisation or operating controls.
What changed and what it means
Counting funded stock before title, quality, release and exit evidence are complete can overstate continuity coverage while financing costs and payment obligations continue.
- Decision affected
- Decide whether each funded supplier-inventory position has enough evidence to be counted as secured, production-ready supply.
- Evidence in brief
- GM’s 8-K and filed IPU agreement establish an up-to-$4.5bn facility, supplier-held inventory and payment obligations that remain independent of delivery, acceptance, quality, insolvency and use.
- What remains unresolved
- Participating suppliers and parts, utilisation, inventory title and segregation, acceptance rules, release mechanics, concentration limits, obsolescence allocation and exit procedures are not disclosed.
- Next verification
- Require a part-level assurance record before any funded quantity enters continuity coverage, then re-test it after funding, acceptance, release and each consumption notice.
Key takeaways
- GM’s programme permits up to $4.5 billion of outstanding IPUs during a 12-month funding period that began on August 7, 2026; it does not show how much has been used.
- Procura is the paying agent, while participating suppliers are to acquire and hold inventory on GM’s behalf.
- Once a confirmation becomes effective, GM’s payment undertaking is independent of delivery, acceptance, quality, insolvency and ultimate use of the goods.
- Procurement should count only part-level quantities supported by title or control, segregation, acceptance, release, ageing, concentration and exit evidence.
What GM’s Procura facility changes
The programme adds a financing layer to GM’s existing vendor contracts and purchase orders. Procura is to obtain bank funding, advance the relevant amounts to suppliers and perform tracking and reporting activities. Suppliers receiving the funds are to acquire and hold inventory until GM needs it for retail or fleet vehicle production.
The availability period runs for 12 months from August 7, 2026. GM disclosed interest at daily simple SOFR plus 1.55% on outstanding IPUs and a 0.25% annual ticking fee on the daily average unused portion of the facility limit during that period. Principal is payable after the applicable inventory is consumed and, in all cases, no later than August 6, 2029. The agreement also permits acceleration after specified GM defaults.
GM will account for supplier prepayments as an asset and each IPU as unsecured debt. Payments made by Procura on GM’s behalf will be presented as an operating cash outflow offset by a financing cash inflow, as though GM had paid the supplier directly. That accounting shows why procurement status must not be inferred from funding status: a recorded prepayment and debt obligation establish financial exposure, not physical availability.
Why prefunding does not make supply assured
Each confirmation may be revoked before the assignee submits the principal wire to the seller account. After that wire, the confirmation becomes effective and irrevocable. From that point, the IPU agreement makes GM’s payment obligation independent of the underlying supplier and Procura arrangements.
The agreement expressly separates payment from failures to deliver, ship or supply; issues with receipt, acceptance or possession; suitability, quality, damage, defects, warranty claims, return rights and non-conformity; Procura or supplier insolvency; whether GM uses the goods; and whether a transfer or security interest is perfected. It also refers to a separate Paying Agency Agreement and Operating Procedures that are not included in the public filing.
This does not establish that GM lacks operational protections. It establishes that the filed payment undertaking does not make those protections a condition of payment. Procurement therefore needs its own evidence gate before a financed position is treated as secured supply.
Eight proofs before procurement counts the stock
The following are Finance Circuit procurement tests, not disclosed GM programme rules. Each should be satisfied for the supplier, facility, part, lot and quantity being recognised.
| Proof point | Evidence procurement should retain | Recognition rule |
|---|---|---|
| Supplier eligibility | Correct legal entity and site, approved supplier status, financial and continuity review, compliance checks and the upstream dependencies that could stop production. | Count zero until the supplier and operating site are approved for the specific part. |
| Part eligibility | Part number, revision, approved source, technical specification, demand basis, intended coverage and any substitution or engineering-change limits. | Do not pool unlike revisions or unapproved substitutes into one coverage figure. |
| Ownership or enforceable control | Contract terms showing who owns or controls the inventory at each stage, priority against competing claims, insurance and rights available if the supplier or warehouse fails. | Seek specialist confirmation where legal title or creditor priority is material; funding alone is not the proof. The same boundary applies to Harvey Nichols pre-pack inventory controls, where acquired stock needs title, cut-off, consignment and exclusion evidence before Day-1 recognition. |
| Segregation and traceability | Warehouse location, tagged lots, serial or batch records, quantity reconciliation, cycle counts and controls preventing unauthorised commingling or substitution. | Recognise only quantities that can be identified and reconciled to the relevant supplier, part and confirmation. |
| Quality acceptance | Required production approval, inspection or test results, shelf-life status, non-conformance records and the party responsible for repair, replacement or return. | Exclude quarantined, expired, damaged or unaccepted units from production-ready coverage. |
| Release and logistics rights | Call-off authority, release service level, transport responsibility, emergency access, customs requirements and an alternate route if the normal warehouse or carrier is unavailable. | Use the executable release quantity and lead time, not the warehouse balance alone. |
| Ageing and obsolescence | Age profile, shelf life, rotation plan, engineering-change exposure, model or programme cancellation rules and allocation of excess and obsolete cost. | Reduce coverage as stock ages or loses approved-use status. |
| Concentration and exit | Common supplier, sub-tier, warehouse, geography and transport dependencies, plus termination, transfer, repurchase, disposal and data-handover arrangements. | Do not claim diversification where the same bottleneck remains, and do not count stock without a workable exit path. |
Build one part-level supply-assurance record
Procurement should maintain one version-controlled record for each supplier, site, part, lot and funded position. It should capture the confirmation reference and funding date, quantity and location, title or control evidence, quality status, accepted quantity, release lead time, ageing, concentration limits, responsible owner and next review date.
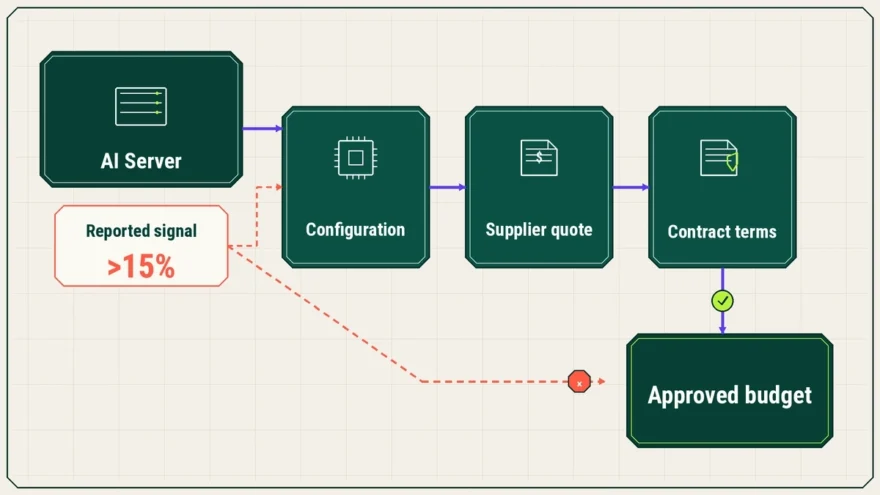
The record should use staged statuses rather than one “prefunded” flag. A practical sequence is funded, located and reconciled, legally controlled, quality accepted, releasable and production-ready. Only the quantity that has reached the final applicable stage should enter base continuity coverage. Any additional stock belongs in a separately labelled scenario until the missing evidence clears.
Finance should reconcile the confirmation amount, supplier-prepayment asset and outstanding IPU. Procurement, quality and logistics should reconcile the physical quantity, acceptance state and release readiness. Differences between those records should be treated as an exception, not averaged into one assurance percentage.
What the public filing does not disclose
GM has not identified the participating suppliers, parts, quantities, storage locations or utilisation. Reuters also reported that the automaker did not specify which parts it considers critical.
The public documents do not set out inventory-title terms, warehouse segregation, quality-acceptance rules, release service levels, obsolescence allocation, concentration limits or exit mechanics. They reference a separate Paying Agency Agreement and Operating Procedures, and the 8-K notes that schedules and similar attachments were omitted. These controls may exist outside the public record. The correct conclusion is “not disclosed,” not “absent.”
What procurement should verify next
Before each confirmation becomes irrevocable, procurement should require a complete supplier-and-part eligibility pack and evidence that the intended stock position has enforceable control, segregation and release terms. At funding, the confirmation, vendor, part, quantity, amount and storage record should reconcile. Before the quantity enters continuity reporting, procurement should obtain physical verification, quality acceptance and a tested release lead time.
On a recurring cadence, the team should reconcile inventory movements, quality holds, ageing, concentration, release exceptions and the Inventory Consumption Notices that drive repayment timing. It should also prepare an end-of-programme plan for remaining stock, including transfer, replenishment, use, return or disposal.
The facility can improve access to supplier funding and inventory, but the amount financed is not the assurance measure. Procurement should report the quantity that can be controlled, accepted and released for a named production need on a stated date.