Revolut Bank S.A. received a full French banking licence on 10 August 2026 following an assessment by France’s ACPR and the European Central Bank, with the decision adopted by the ECB Governing Council. Revolut says the French entity will progressively begin serving customers in France, followed in later phases by Germany, Ireland, Italy, Portugal and Spain. Reuters reports that customers in those markets are to be transferred from Revolut’s Lithuanian entity.
That status matters for finance teams. The licence is granted, but the multi-country migration is planned rather than established as started or complete. For an AP, AR or billing owner, the announcement is not an instruction to change a bank-account master, supplier record, invoice template or collection route. Those records should move only after an account-specific notice establishes the legal entity, identifiers, effective date and transition treatment.
What changed and what it means
Incomplete cutover controls could cause rejected payments, delayed collections, duplicate recurring instructions or reconciliation breaks.
- Decision affected
- Approve or defer payment, collection, billing and master-data changes only after country- and account-specific migration evidence is available.
- Evidence in brief
- Revolut Bank S.A. has a full French licence and is intended to serve France first, followed by Germany, Ireland, Italy, Portugal and Spain in later phases.
- What remains unresolved
- Migration dates, Business-account sequencing, account-detail changes, mandate treatment, interface cutovers and customer-specific terms are not disclosed.
- Next verification
- Wait for the account-specific notice, then test legal entity, bank details, mandates, interfaces, opening balances and exception handling before cutover.
Key takeaways
- Revolut has a full French banking licence, but it has not published a country-by-country customer migration calendar.
- The announcement does not establish that all Revolut Business accounts will move in the same phase or retain the same account details and mandates.
- AP and AR teams should treat the change as a controlled legal-entity, bank-detail, interface and reconciliation cutover.
- Earlier Revolut branch migrations show that mechanics can differ by country; they do not prove the terms of the new French-entity transfer.
What Revolut has licensed, and what remains planned
The verified change is from application to licence. In May 2025, Revolut said it would apply for a French banking licence and build a Western European headquarters in Paris alongside its existing European base in Lithuania.
The August 2026 announcement confirms that Revolut Bank S.A. now has the licence and that France is first in the planned operating sequence. It does not give a first migration date, a completion date, account-level eligibility rules or a separate timetable for Revolut Business. It does not say which account identifiers, mandates, interfaces, fees or statement formats will change.
A licence changes what the entity may do; a customer cutover changes the records through which a business pays, collects and reconciles. The cutover needs evidence. The Deutsche Bank RMB clearing appointment applies the same distinction to payment routing: authorisation is not a client-specific production instruction. The Amazon Business Card issuer cutover gives an August 2026 example: for transferred accounts, balances move while AutoPay settings and third-party card records require separate action.
Treat the move as a controlled legal-entity cutover
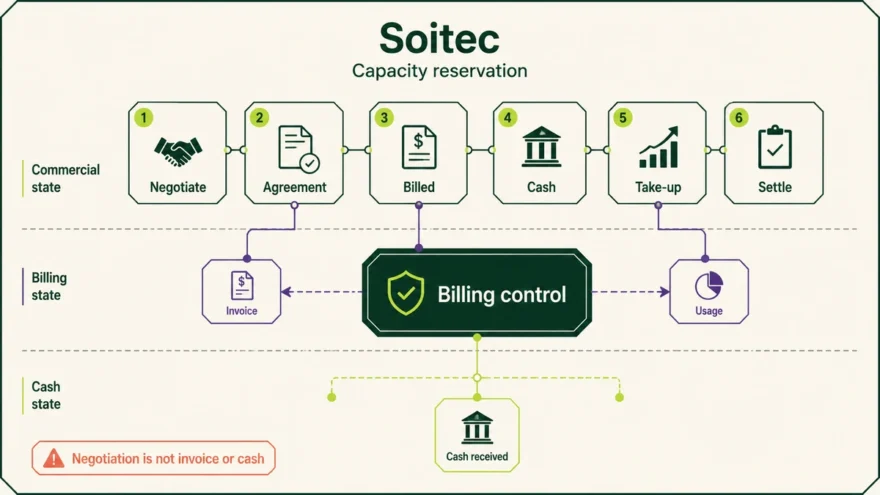
A bank legal-entity transition can touch several finance records even when the customer-facing service appears continuous. The finance systems integration map explains why technical receipt, business acceptance, posting, settlement and reconciliation must remain separate states. The same discipline applies when a bank changes the entity or account structure behind those flows.
| Control area | Evidence required | Acceptance test |
|---|---|---|
| Legal entity and scope | Account-specific notice naming the current and future service provider, country, account and effective date. | The notice agrees to the business entity and account shown in current statements and contracts. |
| Bank identifiers and master data | Confirmed IBAN, BIC, account-holder name, beneficiary details and any overlap period for old identifiers. | Changes are independently verified, approved and effective-dated rather than overwritten early. |
| Outgoing payments | Payment-file, API, approval, cut-off, acknowledgement and rejection requirements for the new route. | A controlled test reaches bank acceptance without duplicate release or an unresolved status. |
| Collections and billing | Customer remittance instructions, invoice wording, Direct Debit treatment, refund routing and portal updates. | Customers receive the correct details and cash application can identify receipts across the transition. |
| Interfaces and statements | Bank-feed identifiers, statement delivery, transaction references, credentials and historical-data access. | Old and new feeds are complete, sequenced and protected from duplicate loading. |
| Close and reconciliation | Final old-entity statement, opening new-entity balance, in-flight item list and accountable exception owner. | Closing and opening populations bridge, with every residual item supported and assigned. |
The order-to-cash handoff model is the relevant control boundary for customer remittance, receipt identification and cash application. For payment files, acknowledgements, statements and fallback routes, use the corporate treasury bank-connectivity guide as the channel-level test.
What earlier Revolut branch migrations show, and do not prove
Revolut already has country-specific branch-migration processes under Revolut Bank UAB. Its French Business help material says eligible France-registered businesses are contacted about migration from an LT IBAN and receive a French IBAN when moved to the French branch, after at least two months’ notice in the described process. French Business branch-migration guidance concerns a branch of the Lithuanian bank, not the newly licensed Revolut Bank S.A.
An Irish Revolut Business help page provides a different operating example. It says the old Lithuanian IBAN remains active for already established recurring payments and Direct Debits after local-branch migration, while customers should share new local details with customers, partners and merchants. Irish Business payment guidance is useful precedent for the control questions, but it is not evidence that the French-entity migration will use the same overlap period or mandate treatment.
These examples support one conclusion: country and account mechanics must come from the notice and terms that govern the specific transfer. A prior Revolut migration is a test case, not a template to copy.
AP and AR acceptance test before cutover
- Fix the population. List each Revolut account, legal entity, country, currency, business use, interface, payment flow and collection flow in scope.
- Wait for controlling notice. Require an account-specific communication and revised terms before changing records. Record the sender, date, effective date and affected account.
- Verify bank-detail changes independently. Separate the person proposing a master-data change from the approver, and confirm the instruction through an authenticated Revolut channel.
- Test both directions. Prove outbound payment acceptance and inbound receipt identification, including rejects, returns, Direct Debits, refunds and recurring instructions.
- Bridge the financial record. Apply the account reconciliation control standard to final and opening statements, balances, in-flight items, duplicates and unresolved differences. The Adyen-Orb control framework applies the same cutover discipline to metered usage, promotion effects, invoices, credits, refunds and settlement records.
- Approve the cutover state. Define who can release the new route, how long the old route remains monitored, what triggers rollback or escalation, and when the old record may be closed.
Potential failures include rejected or misdirected payments, delayed collections, duplicate recurring instructions, stale invoice details and unmatched cash. These are control risks created by an inadequately governed transition, not reported Revolut incidents.
What remains undisclosed and the next verification trigger
Revolut has not disclosed the migration dates, business-account sequence, country-specific eligibility, revised customer terms, identifier treatment, mandate continuity, interface changes, overlap windows, fees, service levels or rollback process for the Revolut Bank S.A. transfer. No source reviewed establishes that every affected account will change in the same way.
The next decision-grade trigger is an account-specific migration notice or published country terms. That evidence should be compared with current statements, contracts, bank details, payment files, customer instructions and reconciliation design before any production change is approved. Until then, the correct finance status is readiness planning, not cutover execution.