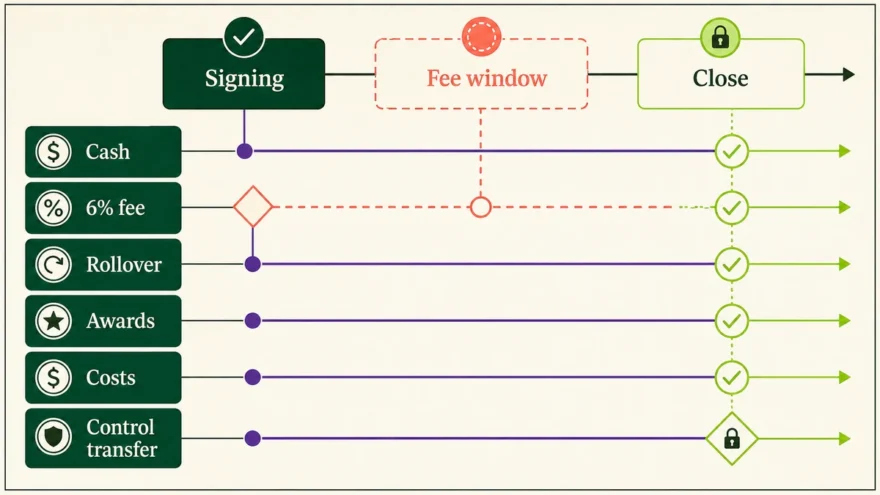
Accelerant’s Thoma Bravo deal: six accounting controls before close
Accelerant’s signed Thoma Bravo deal is not a completed acquisition. Controllers need separate evidence for cash, the ticking fee, rollover, costs and control transfer.
Browse all Finance Circuit reporting, analysis and practical guidance in one place.
Accelerant’s signed Thoma Bravo deal is not a completed acquisition. Controllers need separate evidence for cash, the ticking fee, rollover, costs and control transfer.
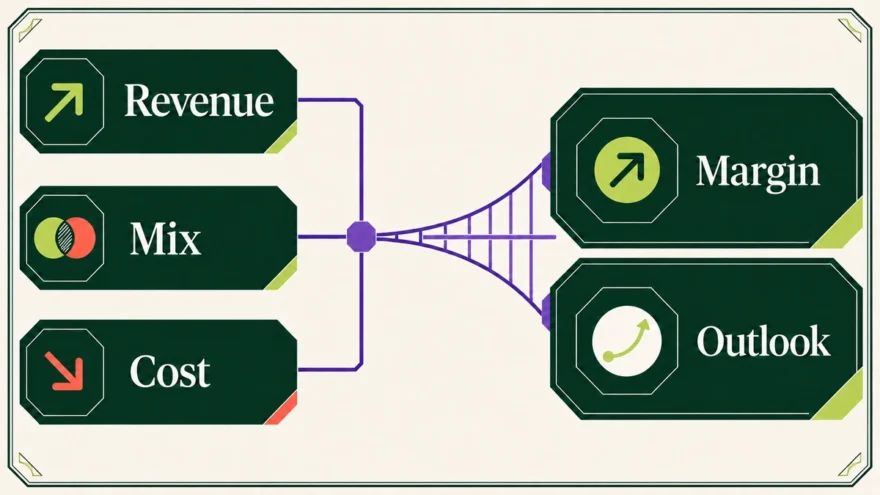
Vestas raised its 2026 EBIT margin before special items to 7–9% after a 9.4% Q2. FP&A should separate project execution, Service, warranty costs and cash conversion before rebasing.
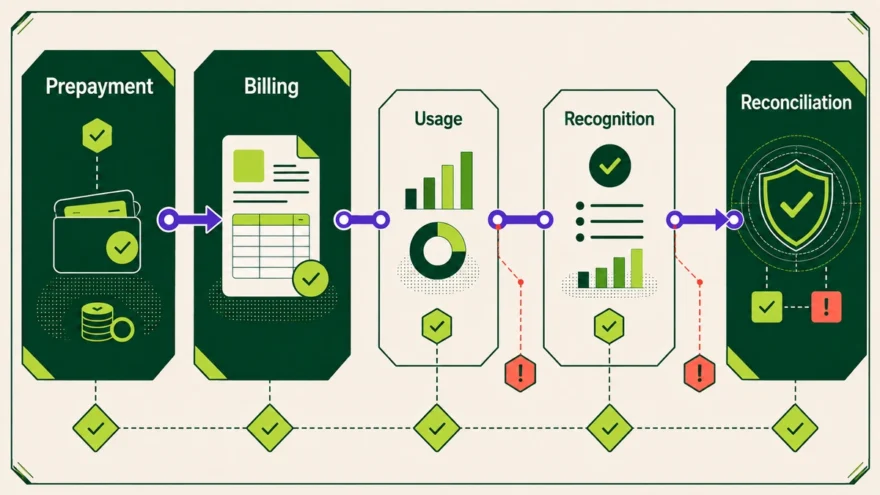
Customer prepayments are set to become a major funding source for Nebius. The control question is how billing teams separate commitments, cash and revenue.
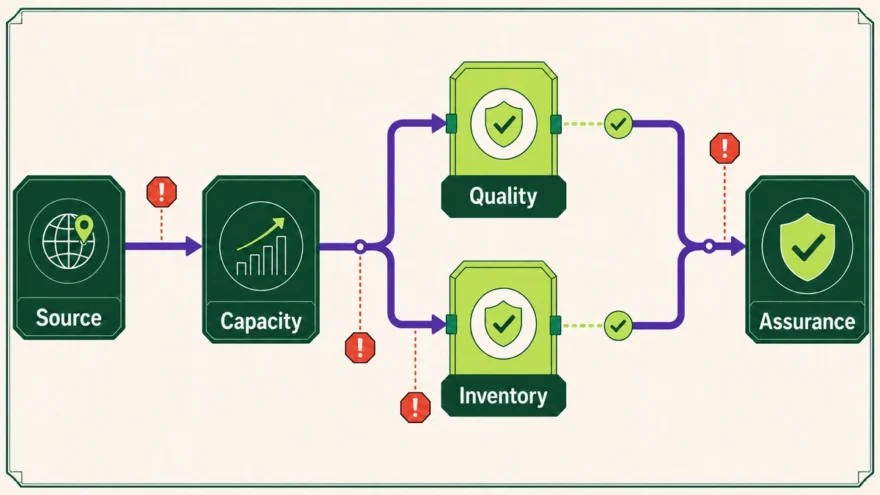
GM entered an up-to-$4.5bn IPU programme for supplier-held critical inventory. Procurement still needs part-level evidence before funded stock counts as secure supply.
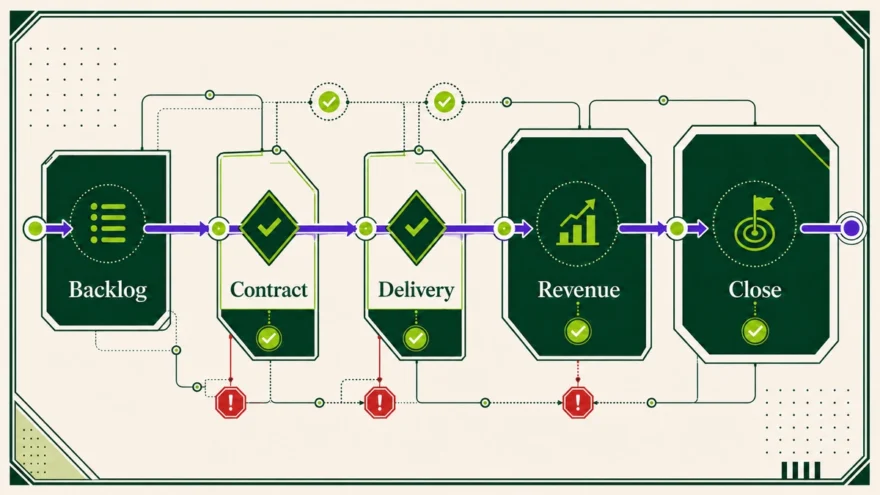
CoreWeave reported $2.575bn in Q2 revenue and $104.2bn of backlog while raising 2026 capex guidance. The filing shows why commitments, contract balances, asset readiness, depreciation and interest need separate close evidence.
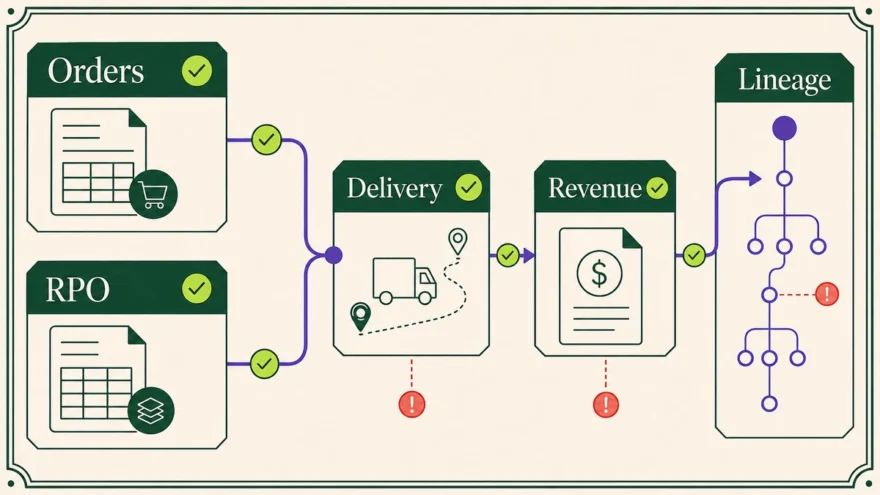
Cisco reported $9.3bn of fiscal 2026 hyperscaler AI-infrastructure orders, but it did not reconcile that order metric to RPO, billing, contract balances or recognized revenue.
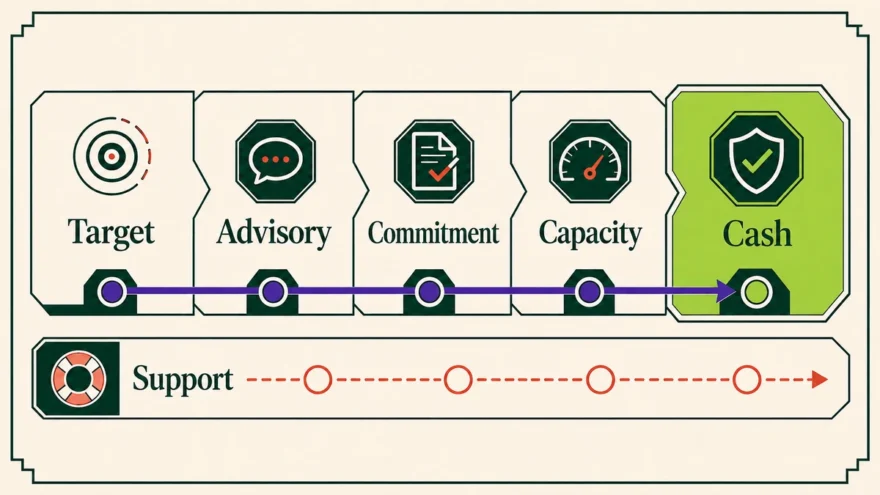
Bank of America’s $250bn target spans lending, investing, capital-markets and advisory activity. Project treasurers need document-level proof before counting committed or drawable funding.
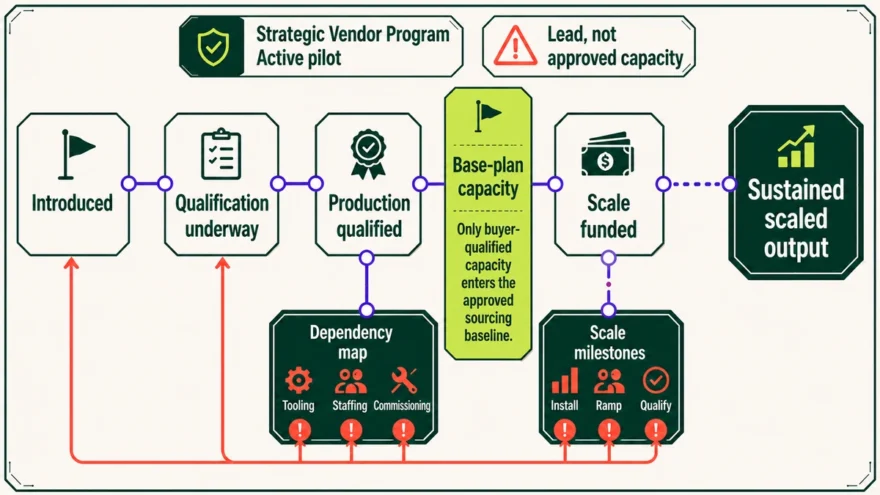
Treasury’s active pilot can surface U.S. suppliers, but procurement should keep proposed capacity outside sourcing plans until qualification, dependency and scale evidence clears review.
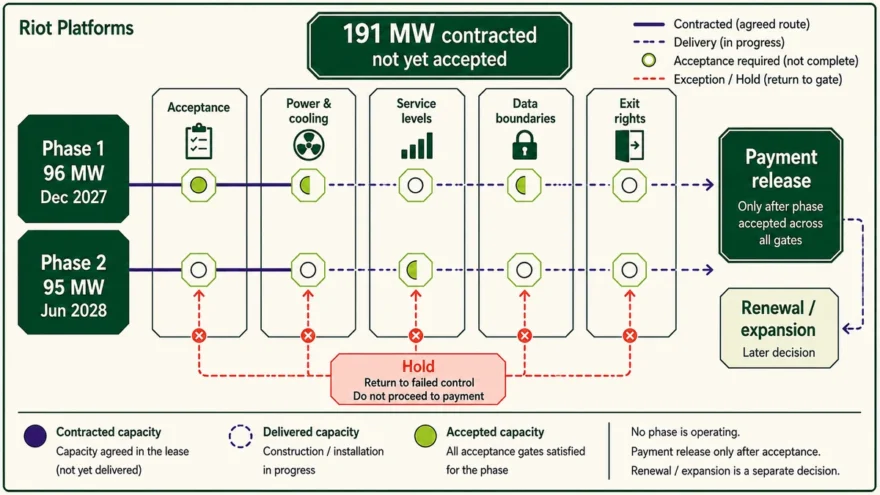
Riot Platforms executed a 20-year lease for 191 MW of phased critical IT capacity. The lease is not attached to the filing, so finance technology leaders should focus on acceptance, utility, service, data and exit protections.
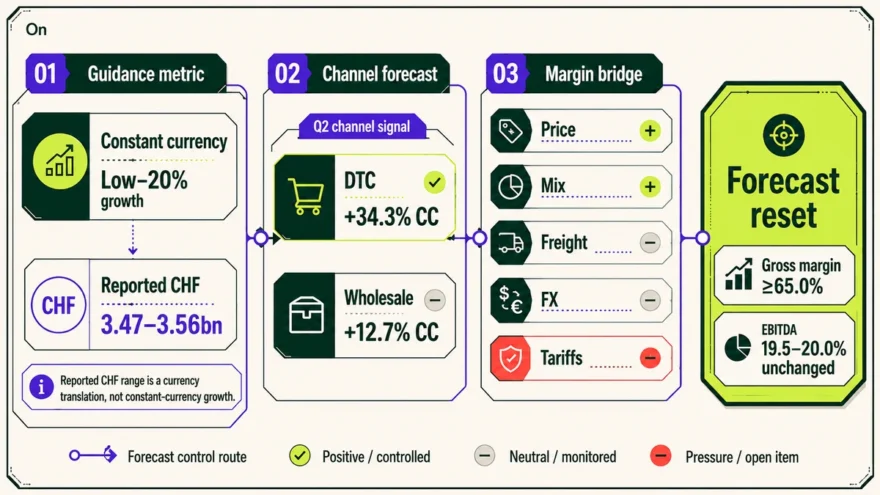
On’s Q2 sales missed consensus, but its revised 2026 outlook pairs a lower sales-growth floor with a higher gross-margin target. FP&A needs a channel, currency and margin bridge before resetting the forecast.